

What Does Medicare Tax Mean?
 By
Medicare tax is the 1.45% line that shows up on every paycheck you have ever received, and unlike Social Security it never stops for the year. If you earn enough, a second 0.9% surtax stacks on top of it. Knowing what those numbers should look like is the difference between spotting a payroll error and paying for one, which is why accurate pay documentation from ThePayStubs matters whether you are checking your own withholding or running payroll for a team. This guide covers the 2026 Medicare tax rate and how it is worked out. It also walks through every filing status threshold for the Additional Medicare Tax, when employers must withhold, how self-employed and contract workers pay, where the tax shows up on your paystub and W-2, and what changed between 2025 and 2026.
Key Takeaways
- The Medicare tax rate is 1.45% for the employee and 1.45% for the employer, or 2.9% total.
- There is no wage base limit for Medicare. Social Security stops at $184,500 in 2026.
- An extra 0.9% Additional Medicare Tax applies above $200,000 (single, head of household, qualifying surviving spouse), $250,000 (married filing jointly) and $125,000 (married filing separately).
- Employers must withhold the 0.9% on any wages over $200,000 regardless of how you file, and there is no employer match on it.
- The 3.8% Net Investment Income Tax is a separate tax on investment income, reported on Form 8960.
- Self-employed workers pay the full 2.9% through self-employment tax on 92.35% of net earnings.
- Nothing about the Medicare figures changed from 2025 to 2026.
- What Is Medicare Tax?
- Medicare Tax Rate 2026: 1.45% Employee, 1.45% Employer
- Is There a Medicare Tax Limit?
- Additional Medicare Tax 2026: The 0.9% Surtax
- Why Your Employer Withholds at $200,000 No Matter How You File
- How Is Medicare Tax Calculated? Two Worked Examples
- Form 8959 Additional Medicare Tax: How You Settle Up at Tax Time
- The 3.8% Net Investment Income Tax Is a Separate Tax
- Medicare Tax for Self-Employed and 1099 Workers
- Where Medicare Tax Shows Up on Your Paystub and W-2
- Pay That Is Exempt From Medicare Tax
- What Changed Between 2025 and 2026
- Conclusion: Keeping Your Medicare Tax Records Straight
What Is Medicare Tax?
Medicare tax is a federal payroll tax that funds Medicare Part A hospital insurance. It is collected under FICA, and almost everyone with covered wages pays it. Employees pay 1.45% of gross wages, employers match that 1.45%, and self-employed workers cover the full 2.9% themselves through self-employment tax.
That is the whole setup. It is worth knowing what the money does. The Medicare payroll tax feeds the trust fund that pays for inpatient hospital stays, skilled nursing care and hospice for current beneficiaries. It is not a premium for a plan you hold today. It pays into a program you qualify for later. That is the answer to a question we get constantly from readers who already have health coverage at work.
Medicare tax travels with Social Security tax under the Federal Insurance Contributions Act, which is why the two are so often discussed together and why understanding what FICA stands for clears up most paystub confusion in one go. Both are payroll taxes, so they are tied to what you earn rather than to your whole tax picture. That makes them behave very differently from the federal income tax that also comes out of your check. If that distinction is fuzzy, our breakdown of payroll tax versus income tax is the shortest route to clarity.
Medicare Tax Rate 2026: 1.45% Employee, 1.45% Employer

The Medicare tax rate has not moved since 1986, and it is charged as a flat percentage of gross pay rather than on a bracket system, so it does not step up as you move through the income scale. The IRS states it plainly in Topic 751: "The current rate for Medicare is 1.45% for the employer and 1.45% for the employee, or 2.9% total."
Here are the Social Security and Medicare tax rate 2026 figures side by side, because the contrast between them explains almost every question people have about their December paystub.
| Tax | Employee rate | Employer rate | Combined | 2026 wage base |
|---|---|---|---|---|
| Medicare | 1.45% | 1.45% | 2.9% | None, all covered wages |
| Social Security | 6.2% | 6.2% | 12.4% | $184,500 |
| Additional Medicare Tax | 0.9% | 0% (no match) | 0.9% | Applies above threshold only |
The pattern is easy to read once the three sit side by side. So how much is Medicare tax on a real paycheck? On $5,000 of gross covered wages, the employee Medicare tax is $72.50, and your employer quietly pays another $72.50 that never appears on your stub. On an $80,000 salary, you contribute $1,160 across the year and your employer contributes the same.
For employers, the practical point is that the 1.45% never switches off. There is no point in the year where you stop owing the employer match. Social Security does the opposite once an employee passes the wage base.
Is There a Medicare Tax Limit?
No. There is no wage base limit for Medicare tax, so the 1.45% comes out of every dollar of covered wages all year long. Social Security is different: it stops once you reach the 2026 wage base of $184,500. That contrast is why Medicare keeps appearing on December paystubs.
This one difference causes more payroll questions than anything else on this page. An employee earning $220,000 sees Social Security withholding stop partway through the year and assumes Medicare will stop too. It does not. The IRS is unambiguous: "There's no wage base limit for Medicare tax. All covered wages are subject to Medicare tax."
For the other half of that picture, our guide to how much Social Security tax you actually pay covers the wage base in detail. For a small business owner, the lesson is simple. Your Social Security cost for a highly paid worker is capped and steady. Your Medicare cost grows with every raise and every bonus you hand out.
Additional Medicare Tax 2026: The 0.9% Surtax

The Additional Medicare Tax is a 0.9% surtax that took effect on January 1, 2013. The IRS phrasing is short: "The rate is 0.9 percent." It applies to wages, railroad retirement compensation and self-employment income once your total passes the threshold for your filing status.
Two things set this tax apart from everything else on your paystub. First, there is no employer match. The IRS answers the question directly: "No. There is no employer match for Additional Medicare Tax." Second, the 0.9% hits only the dollars above your threshold, never your whole income. Someone who crosses the line by $30,000 pays 0.9% on that $30,000, not on their full salary.
People still look up the Medicare surtax 2025 figures while preparing a 2025 return during 2026, and the good news is that they match 2026 exactly. The additional Medicare tax 2025 threshold is $200,000, $250,000 or $125,000, depending on how you file. These are statutory dollar amounts, and they have not moved since the tax took effect in 2013. That is why every additional Medicare tax 2026 figure is identical.
Additional Medicare Tax Threshold 2026 by Filing Status
| Filing status | Threshold |
|---|---|
| Married filing jointly | $250,000 |
| Married filing separately | $125,000 |
| Single | $200,000 |
| Head of household | $200,000 |
| Qualifying surviving spouse | $200,000 |
Source: IRS, Questions and Answers for the Additional Medicare Tax, page last updated 11 August 2026.
One row deserves a warning label. The additional Medicare tax threshold married filing jointly couples share is $250,000 in combined wages and self-employment income, not $250,000 each. A couple earning $150,000 and $140,000 has combined earnings of $290,000, which puts $40,000 over the threshold and creates a real surtax bill, even though neither spouse is remotely close to $250,000 on their own. Their employers, looking at each salary in isolation, will have withheld nothing extra all year.
By contrast, the additional Medicare tax threshold single filer households face is $200,000, which is also the figure every employer withholds against. That alignment is why single high earners rarely get a surprise and dual-earner couples so often do.
Why Your Employer Withholds at $200,000 No Matter How You File
Here is the rule that causes nearly all of the confusion: "An employer must withhold Additional Medicare Tax from wages it pays to an individual in excess of $200,000 in a calendar year." That $200,000 trigger is fixed. Your employer does not know your filing status here. It does not know your spouse's income. It is not allowed to move the trigger for either one.
So withholding and what you actually owe are two different numbers. They match only sometimes:
- Single filer at $230,000. Employer withholds 0.9% on $30,000. Actual threshold is also $200,000. Withholding and liability match.
- Married couple at $150,000 plus $140,000. Neither employer withholds anything extra, because neither salary exceeds $200,000. Actual liability is 0.9% on $40,000 of combined earnings. The couple is under-withheld and owes at filing.
- Married filing separately at $210,000. Employer withholds on $10,000. The actual threshold is $125,000, so real liability is 0.9% on $85,000. Badly under-withheld.
- Single filer at $205,000 who changed jobs. Each employer stayed under $200,000, so neither withheld. Liability still applies on $5,000.
None of this is a payroll error. It is the rule working as written. Employers must not tune the trigger to an employee's personal situation. An employee can, however, ask for extra federal income tax withholding on a Form W-4 to soften the bill. Employees who see the medicare tax withheld figure climbing mid-year now know why.
How Is Medicare Tax Calculated? Two Worked Examples
Multiply your gross covered wages by 1.45%. If your wages pass your filing status threshold, add 0.9% on the amount above it, so those dollars are taxed at 2.35% total. The extra 0.9% applies only to the excess, never to your whole salary, and your employer never matches it.
Example 1: single filer earning $230,000.
- Base Medicare tax: $230,000 x 1.45% = $3,335
- Amount over the $200,000 threshold: $30,000
- Additional Medicare Tax: $30,000 x 0.9% = $270
- Total Medicare tax for the employee: $3,605
- Employer pays: $3,335 (the 1.45% match only, nothing on the surtax)
Only that top $30,000 is taxed at the combined 2.35%. The first $200,000 is taxed at 1.45%, which is why quoting "2.35%" as if it applied to a whole salary is wrong.
Example 2: married couple filing jointly, $150,000 and $140,000.
- Combined wages: $290,000
- Base Medicare tax taken from both jobs: $290,000 x 1.45% = $4,205
- Amount over the $250,000 joint threshold: $40,000
- Additional Medicare Tax owed: $40,000 x 0.9% = $360
- Amount either employer withheld toward that surtax: $0
That $360 shows up as a balance due at tax time. This is the case that catches households off guard every spring. The fix is simply knowing it is coming.
Form 8959 Additional Medicare Tax: How You Settle Up at Tax Time
Withholding is an estimate. Form 8959 is where the estimate meets reality. The IRS puts it this way: "Individuals will calculate Additional Medicare Tax liability on their individual income tax returns (Form 1040 or 1040-SR), using Form 8959, Additional Medicare Tax."
The form does three jobs in order. It adds up your Medicare wages, railroad retirement pay and self-employment income. It applies your filing status threshold to that total. Then it checks what you owe against what your employers took out.
It works both ways. If too little came out, as with the couple in Example 2, the gap moves to your Form 1040 as tax owed. If too much came out, you can recover excess Medicare tax 2025 withholding on Form 8959 when you file that return. The extra then becomes a credit against your total tax. That is the real answer for anyone who has typed "do I get my Medicare tax back" into a search bar: you do not get the 1.45% back, but you absolutely can get an over-withheld 0.9% back.
The 3.8% Net Investment Income Tax Is a Separate Tax
The two surtaxes get mixed up constantly. They are not the same tax. The Net Investment Income Tax is 3.8% and it also started on January 1, 2013. It applies to investment income rather than earnings: interest, dividends, capital gains, rental and royalty income and non-qualified annuities. You report it on Form 8960.
Critically, the IRS states that the two do not overlap: "You may be subject to both taxes, but not on the same type of income. The 0.9 percent Additional Medicare Tax applies to individuals' wages, compensation, and self-employment income over certain thresholds, but it does not apply to income items included in Net Investment Income."
| Filing status | NIIT MAGI threshold |
|---|---|
| Married filing jointly | $250,000 |
| Married filing separately | $125,000 |
| Single or head of household | $200,000 |
| Qualifying widow(er) with a child | $250,000 |
Source: IRS, Net Investment Income Tax, page last reviewed 1 July 2026.
Compare that last row against the surtax table above and you will spot something almost nobody prints. A qualifying surviving spouse hits the 0.9% Additional Medicare Tax at $200,000. The 3.8% NIIT does not start until $250,000. Two IRS pages, two figures, for what sounds like the same filing status. If that is you, use each table for its own tax. Do not assume one threshold covers both.
One more point worth holding onto. The NIIT is charged on the lesser of two things: your net investment income, or the amount your modified adjusted gross income sits above the threshold. Wages, unemployment compensation, Social Security benefits and most self-employment income are excluded from net investment income entirely.
Medicare Tax for Self-Employed and 1099 Workers
When you work for yourself, you are both halves of the deal. Self-employment tax is 15.3%, which the IRS breaks down as "12.4% for Social Security and 2.9% for Medicare taxes." There is no separate 1099 Medicare tax hiding somewhere. Contractors pay the same 2.9%, just all at once instead of split with an employer.
Three details change the arithmetic:
- You are taxed on 92.35% of net earnings. The IRS: "Generally, the amount subject to self-employment tax is 92.35% of your net earnings from self-employment." On $100,000 of net earnings, the Medicare portion applies to $92,350, so 2.9% of that is $2,678.15.
- The Medicare portion is uncapped. "All of your net earnings are subject to the Medicare tax." The Social Security portion stops at $184,500 for 2026, and the Medicare portion never does.
- You deduct half of the self-employment tax. When figuring adjusted gross income, you deduct one-half of your self-employment tax. Note carefully that this covers the 15.3% self-employment tax only. The 0.9% Additional Medicare Tax sits outside that deduction and is figured on its own form.
The same thresholds apply to self-employment income. Wages and self-employment income are added together first. A contractor with $120,000 of net earnings and a spouse earning $160,000 is over the joint threshold on their combined total, even though the business alone is nowhere near it.
Any 1099 tax calculator 2026 estimate is only as good as the net earnings figure you feed it. Clean books matter more than the calculator. For a full walkthrough of the numbers, see our guide on calculating tax on 1099-MISC income.
Where Medicare Tax Shows Up on Your Paystub and W-2
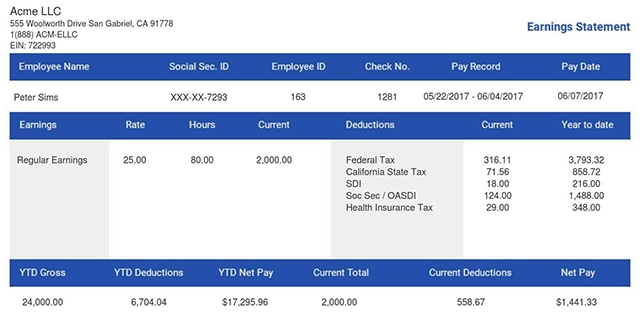
What is Medicare tax on my paycheck actually labeled? On most paystubs it appears as "Medicare", "Med" or "FICA-MED", listed as its own line separate from Social Security. On your W-2 it occupies two boxes:
- Box 5, Medicare wages and tips: every dollar of covered wages, with no cap applied.
- Box 6, Medicare tax withheld: the total dollar amount taken out, including any 0.9% surtax your employer withheld.
Box 5 is the box people misread. It is often larger than Box 1 (wages, tips and other pay), because 401(k) contributions cut Box 1 but not Box 5. It is also larger than Box 3 (Social Security wages) for anyone earning above $184,500, since Box 3 stops at the wage base and Box 5 does not. Two boxes that disagree is normal, not a mistake. Our explainer on Social Security wages on your W-2 covers the other side of that comparison.
A fast sanity check: divide Box 6 by Box 5. If you get 1.45%, your withholding is standard. If you get something between 1.45% and 2.35%, your employer withheld some Additional Medicare Tax, so your wages passed $200,000 there. Employers should run the same check before issuing W-2s. Box 5 and Box 6 errors are among the most common reasons a W-2 correction gets filed.
Pay That Is Exempt From Medicare Tax
Covered wages include salaries, hourly pay, bonuses and commissions, but not every dollar your employer spends on you counts. IRS Publication 15-B for 2026 lists the fringe benefits that sit outside Social Security and Medicare tax:
| Benefit | Medicare treatment |
|---|---|
| Accident and health benefits | Exempt |
| Health savings account contributions | Exempt for qualified individuals up to HSA contribution limits |
| Dependent care assistance | Exempt up to $7,500 for 2026 ($3,750 if married filing separately) |
| Group-term life insurance | Exempt up to the cost of $50,000 of coverage |
Pre-tax cafeteria plan choices follow the same logic. If an employee picks a nontaxable benefit, it is treated as if the benefit came from outside the plan. If they take cash instead, it is subject to all employment taxes.
For employees, this is why your Medicare wages in Box 5 may be lower than your salary on paper. For employers, sorting these benefits correctly is what keeps taxable wages right on every stub you issue. Get it wrong and it comes back later as a payroll correction.
What Changed Between 2025 and 2026
For Medicare specifically, nothing did.
| Figure | 2025 | 2026 |
|---|---|---|
| Employee Medicare rate | 1.45% | 1.45% |
| Combined Medicare rate | 2.9% | 2.9% |
| Medicare wage base limit | None | None |
| Additional Medicare Tax (surtax) | 0.9% | 0.9% |
| Surtax thresholds | $200,000 / $250,000 / $125,000 | $200,000 / $250,000 / $125,000 |
| Net Investment Income Tax | 3.8% | 3.8% |
| Social Security wage base | $176,100 | $184,500 |
The only number that moved is the Social Security wage base, now $184,500 for 2026. That changes your total FICA withholding. It does not touch Medicare at all. If you are filing a 2025 return during 2026, every Medicare figure you need is printed above.
Conclusion: Keeping Your Medicare Tax Records Straight
Medicare tax is simple at heart: 1.45% on everything. It gets tricky at the edges, where the 0.9% surtax, employer withholding rules and filing status thresholds meet. Two habits prevent surprises. Check Box 5 against Box 6 once a year. Run your household's combined earnings against your filing status threshold in December, not in April.
Good records make all of that possible. Maybe you need proof of income for a rental application, clean records for a contractor's tax filing, or professional stubs for the people you pay. You can create a detailed pay stub with ThePayStubs in a couple of minutes, with every Medicare tax line worked out and itemized correctly from the start.
You Might Also Like
- 1. Enter Your Information

- 2. Select Your Favorite Theme

- 3. Download Your Stub!

 By