

Summary Plan Description (SPD): What It Covers in 2026
 By
Most people never read the benefits guide their employer hands out. Then a claim gets denied, or a 401(k) match looks off on a pay stub. That guide is the summary plan description, and it explains your work benefits in plain words. Small business owners meet it when they add a group health plan. Here's what it says, when you get it, and how to use it.
Key Takeaways
- An SPD explains a benefit plan's rules, costs, and your rights under federal law.
- Employers must give it free to plan participants within 90 days of coverage.
- The plan document is the legal rulebook; the SPD is the readable summary.
- Ask for a copy in writing, and the plan has 30 days to send it.
What Is a Summary Plan Description?
A summary plan description (SPD) is a plain-language guide to an employee benefit plan. Under the Employee Retirement Income Security Act (ERISA), employers must give it free to plan participants. It explains who can join, what the plan pays, how vesting works, how to file a claim, and your legal rights.
It turns a long legal plan into something a worker can follow. The Department of Labor's Employee Benefits Security Administration enforces the rule. It's the first place to look when you have a question about your coverage.
What Is SPD in Healthcare?
In healthcare, an SPD is the document that explains your employer's group health plan. It lists covered services, cost sharing, eligibility rules, and the claims and appeals process. The insurance company's booklet often covers part of this, but the employer is responsible for the complete SPD.
That's why SPD insurance booklets aren't always enough alone. Many employers add a short "wrap" document to fill the gaps. At larger employers (250+ W-2s), the total cost of that coverage is also reported on your W-2 in Box 12, code DD.
What a Summary Plan Description Includes

Federal rules at 29 CFR 2520.102-3 list what every SPD must contain. The core items are:
- The plan name, plan number, and type of plan
- The employer's name, address, and EIN
- The plan administrator's name and contact details
- Who is eligible and when coverage starts
- How benefits are earned, paid, and lost
- The vesting schedule for retirement plans
- The plan year and how it is funded
- How to file a claim and appeal a denial
- A statement of your ERISA rights
When I review a benefits packet, I start with the claims section. Then I check when you're eligible, how fast you vest, the claim deadline, and what happens to your SPD benefits if you leave.
Who Must Provide an SPD?
The plan administrator, usually the employer, must provide an SPD for most private-sector benefit plans covered by ERISA. That includes group health, dental, vision, life, and disability coverage, plus 401(k) and pension plans. Government plans and most church plans are exempt from the rule.
Health FSAs and HRAs count, too. Part-time workers who join a plan get one as well. Employers don't file the SPD with the Department of Labor. Still, the agency can ask for a copy, and you must hand it over.
When Do You Receive Your Summary Plan Description?

You should receive your SPD within 90 days of becoming covered by the plan. A brand-new plan has 120 days after it becomes subject to ERISA. If you ask in writing, the plan administrator must send a copy within 30 days, at no charge.
| Event | Deadline |
|---|---|
| You join the plan | Within 90 days of coverage |
| New plan is set up | Within 120 days |
| You ask in writing | Within 30 days |
| Health plan cuts covered services | Within 60 days of adoption |
| Other plan changes | Within 210 days after the plan year ends |
| Updated SPD (plan was amended) | Every 5 years |
| Updated SPD (no changes) | Every 10 years |
Changes between updates go out in a summary of material modifications. Plans can send these by email if they follow safe harbor rules, but you can always ask for paper. The IRS guide for plan participants confirms the 90-day rule.
Some plans have many workers who read only another language. In that case, the SPD must include a notice in that language that offers help.
Summary Plan Description vs. Plan Document
People sometimes say "summary plan document," but these are two separate papers.
| Plan Document | Summary Plan Description | |
|---|---|---|
| Purpose | Legal rules for running the plan | Plain explanation of benefits |
| Audience | Plan administrators | Plan participants and beneficiaries |
| Length | Long and technical | Shorter and readable |
| If they conflict | Usually controls | Can support a claim if it misled you |
In 2011, the U.S. Supreme Court ruled in CIGNA Corp. v. Amara that the SPD isn't part of the plan's terms. So the plan document usually wins in a dispute.
How to Use Your SPD With Your Pay Stub
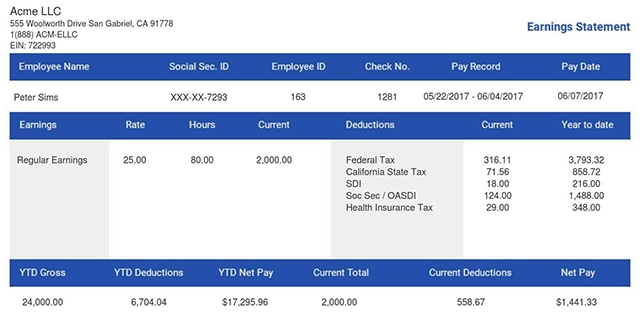
New hires often ask, "What is a SPD, and why should I care?" Here's one good answer: it explains why money comes out of your check. Your pay stub shows how much. Put them side by side.
- Find the health premium and 401(k) lines on your latest stub.
- Check them against the rates in your SPD healthcare and retirement sections.
- Confirm the employer match follows the plan's formula.
- Ask HR in writing for the SPD if you can't find it online.
Save a PDF of your SPD next to your recent pay stubs. You'll have the rule and the paycheck record in one place. Need clean pay records for a loan or lease? Here's how to get a check stub for a loan fast.
If you run payroll, keep every benefit deduction in line with the SPD. When the stub and the plan say two different things, employees notice, and that's usually how disputes start.
Employer Checklist and Penalties
Pair these steps with your regular HR payroll compliance routine.
- List every plan that ERISA covers.
- Collect insurer booklets and add a wrap SPD for missing items.
- Include the ERISA rights statement.
- Set calendar reminders for the 90, 120, and 210 day deadlines.
- Track every change and send updates on time.
- Keep proof of delivery for each employee.
Skipping a written request can cost a lot. A court can fine the plan administrator up to $110 per day after the 30-day window.
You Might Also Like
- How to Read Pay Stub Deduction Codes
- How to Read a W-2 Like a Pro
- How to Acquire an Earnings Statement
- How to Calculate W-2 Wages From a Pay Stub
- What Does a Benefits Administrator Do?
Conclusion
Your SPD tells you what your benefits are, how to use them, and what to do when something goes wrong. Read it once, save it, and check it against your pay stubs each year. Need clear pay records for yourself or your team? Try our paystub generator to create accurate stubs in minutes.
- 1. Enter Your Information

- 2. Select Your Favorite Theme

- 3. Download Your Stub!

 By